GSTR-1 vs GSTR-3B: Filing Checklist for Amazon and Flipkart Sellers
Missing the difference between GSTR-1 and GSTR-3B costs marketplace sellers interest, penalties, and blocked ITC — here is exactly what to file, when, and how.
 AKSHAY AGARWAL Sep 22, 2026
GSTR-1 reports your sales invoice-by-invoice while GSTR-3B is where you actually pay tax, and the portal automatically flags mismatches above Rs 25 lakh or 20% under Rule 88C, triggering a DRC-01B notice with 18% interest. Marketplace sellers must reconcile Amazon and Flipkart settlement reports against GSTR-2B before filing, especially to catch TCS credits that frequently get missed or claimed in the wrong month. Multi-state registrations through VPOB arrangements multiply late fees across every GSTIN, so missing deadlines costs significantly more than single-state sellers expect.
Most Amazon and Flipkart sellers treat GSTR-1 and GSTR-3B as two boxes to tick each month, without understanding that errors in one directly corrupt the other — and that the GST portal will flag the mismatch automatically under Rule 88C.
What each return actually does
GSTR-1: the outward supply statement
GSTR-1 is a declaration of every sale you made during the period. Under Section 37 of the CGST Act, 2017, you report invoice-level details: GSTIN of B2B buyers, HSN codes, taxable value, and the tax charged. For marketplace sellers, this includes:
- B2C sales to end customers (reported aggregate in Table 7 if invoice value is below Rs 2.5 lakh, or invoice-wise in Table 5 for inter-state supplies above that threshold)
- B2B sales to GST-registered resellers (Table 4)
- Credit notes and debit notes (Tables 9 and 9B)
- Supplies through e-commerce operators where TCS under Section 52 applies (Table 8 — ECO supplies)
GSTR-1 does not involve any payment. It is purely informational. Once filed, it populates the buyer's GSTR-2B, which is why accuracy here is non-negotiable.
GSTR-3B: the self-assessed summary return
GSTR-3B, governed by Rule 61 of the CGST Rules, is a summary return where you self-declare total outward tax liability, eligible ITC, and the net tax payable. Payment of GST happens here — through the electronic cash ledger or by utilizing ITC from the electronic credit ledger.
The critical point: GSTR-3B values must match GSTR-1 values. Since November 2022, the portal enforces Rule 88C, which triggers a system-generated notice (DRC-01B) if the difference between GSTR-1 liability and GSTR-3B liability exceeds Rs 25 lakh or 20 percent of GSTR-3B liability, whichever is lower. Sellers who ignore DRC-01B face interest under Section 50 at 18 percent per annum.
How marketplace TCS affects both returns
Amazon (via Amazon Seller Services Pvt Ltd) and Flipkart (via Flipkart Internet Pvt Ltd) deduct Tax Collected at Source at 1 percent (0.5 percent CGST + 0.5 percent SGST, or 1 percent IGST) on the net value of taxable supplies made through their platforms, under Section 52 of the CGST Act.
Get Expert GST and
Compliance Services
VPOB · COMPLIANCE · ACCOUNTING · AUDIT
Contact us
This TCS credit appears in your GSTR-2B automatically once the operator files GSTR-8. You must claim it in Table 8 of GSTR-3B (TCS credit received). Sellers frequently miss this or claim it in the wrong period, leading to excess cash outflow. Reconcile your monthly settlement reports from Seller Central or Flipkart Seller Hub against the TCS figure in GSTR-2B before filing GSTR-3B.
Filing deadlines and late fees
Standard monthly deadlines
| Return | Taxpayer category | Due date |
|---|---|---|
| GSTR-1 | Turnover above Rs 5 crore (monthly) | 11th of following month |
| GSTR-1 | QRMP opted (quarterly) | 13th of month after quarter |
| IFF (Invoice Furnishing Facility) | QRMP — optional monthly upload | 13th of following month |
| GSTR-3B | Turnover above Rs 5 crore | 20th of following month |
| GSTR-3B | QRMP — category A states | 22nd of month after quarter |
| GSTR-3B | QRMP — category B states | 24th of month after quarter |
Maharashtra, Karnataka, and most high-volume e-commerce states fall under Category A for QRMP purposes.
Late fee structure
Under Section 47 of the CGST Act:
- GSTR-1 late fee: Rs 50 per day (Rs 25 CGST + Rs 25 SGST) for returns with tax liability; Rs 20 per day for nil returns. Maximum cap of Rs 10,000 per return.
- GSTR-3B late fee: Same Rs 50 / Rs 20 per day structure with the same Rs 10,000 cap per Act (so Rs 20,000 total including SGST Act for a non-nil return).
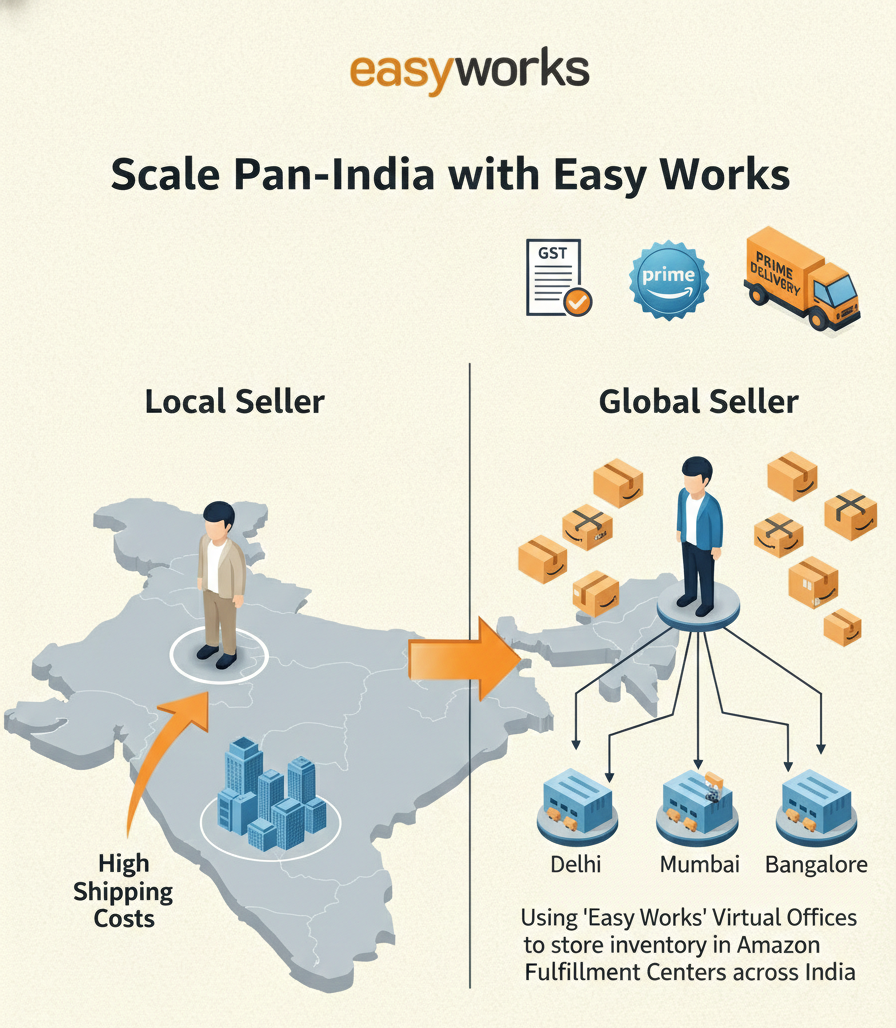
For sellers registered in multiple states — common when using VPOB or APOB arrangements to comply with marketplace warehousing requirements — late fees accrue separately for each state registration. A seller with five state GSTINs filing GSTR-3B 10 days late on a non-nil return pays up to Rs 2,500 per GSTIN, or Rs 12,500 total across five states.
Pre-filing checklist for marketplace sellers
Before filing GSTR-1
- Download the monthly GST sales report from Amazon Seller Central (Reports > Tax Document Library > GST Sales Report) and Flipkart Seller Hub. These reports carry invoice numbers, GSTINs, HSN codes, and tax amounts.
- Cross-check total taxable value and tax in the report against your own books or accounting software.
- Confirm all B2B invoices carry the buyer's GSTIN — missing GSTINs force you to report the supply as B2C, which cannot then be amended to B2B after the return is filed for the period.
- Verify HSN codes are at 4-digit level if annual turnover is between Rs 5 crore and Rs 50 crore, or 8-digit level above Rs 50 crore, as required under Notification 78/2020-Central Tax.
- Check credit notes issued for returns and cancellations — these must appear in Table 9B of GSTR-1 for the period in which the credit note was issued, not the period of the original invoice.
Before filing GSTR-3B
- Pull your GSTR-2B for the period and reconcile every ITC line. Only ITC reflected in GSTR-2B is eligible for claim under Section 16(2)(aa) of the CGST Act — provisional ITC is no longer permitted.
- Verify TCS credit in GSTR-2B matches the TCS amount on your marketplace settlement statements. Amazon files GSTR-8 by the 10th of the following month; the credit typically becomes visible in GSTR-2B between the 12th and 14th.
- Ensure total outward tax liability in GSTR-3B matches what you reported in GSTR-1. Any difference must be explainable and should be within Rule 88C thresholds to avoid DRC-01B.
- Block ITC under Section 17(5) for any ineligible expenses — food, personal use, club memberships — before claiming net ITC.
- Confirm payment through the electronic cash ledger is sufficient to cover liability after ITC set-off. IGST credit offsets IGST first, then CGST; CGST credit cannot offset SGST and vice versa, per Section 49 of the CGST Act.
Common reconciliation failures specific to e-commerce sellers
- Returns processed across months: A customer return processed in March for a February order creates a credit note in March. Sellers sometimes backdate it to February, creating a mismatch in both periods.
- Multi-state warehouse inventory moves: Stock transfers between Amazon fulfillment centers in different states are treated as branch transfers (supply under Schedule I of the CGST Act if not between registered GSTINs) and must appear in GSTR-1 as Table 4 supplies against the destination GSTIN.
- Meesho and other platforms without mandatory TCS: Not all marketplaces deduct TCS — Meesho currently deducts TCS; however, you must independently verify each operator's GSTIN and check GSTR-2B to confirm the credit has been filed rather than assuming it.
Amendments and corrections after filing
GSTR-1 can be amended in the subsequent period's GSTR-1 using Tables 9 and 10 (B2B and B2C amendments respectively). You cannot file a revised GSTR-1 for a completed period — the amendment mechanism is the only route.
GSTR-3B cannot be amended directly. If you under-reported liability in GSTR-3B, the correct approach is to report the differential in the next GSTR-3B along with interest under Section 50. If you over-reported and paid excess tax, the refund route under Section 54 applies, but for most marketplace sellers a set-off in the next period is faster.
The Annual Return in GSTR-9 (mandatory for turnover above Rs 2 crore) is where cumulative mismatches across twelve months surface. Sellers who reconcile monthly find GSTR-9 to be a formality; those who do not often discover large gaps in April that require paid reconciliation services to resolve.
Conclusion
GSTR-1 and GSTR-3B serve different functions — one is the invoice-level record, the other is the payment mechanism — but the GST system treats them as a matched pair. Marketplace sellers who reconcile their Amazon, Flipkart, and Meesho settlement data against both returns before filing avoid DRC-01B notices, interest under Section 50, and the compounding problem of errors carrying into GSTR-9.
If your current process is download-and-upload without a reconciliation step, that is where the risk lives. EasyWorks handles end-to-end GST compliance for marketplace sellers, including VPOB and APOB registrations across states.
Book a free consultation to review your filing process and identify any open mismatches before your next due date.
Get Expert GST and
Compliance Services
VPOB · COMPLIANCE · ACCOUNTING · AUDIT
Contact us